
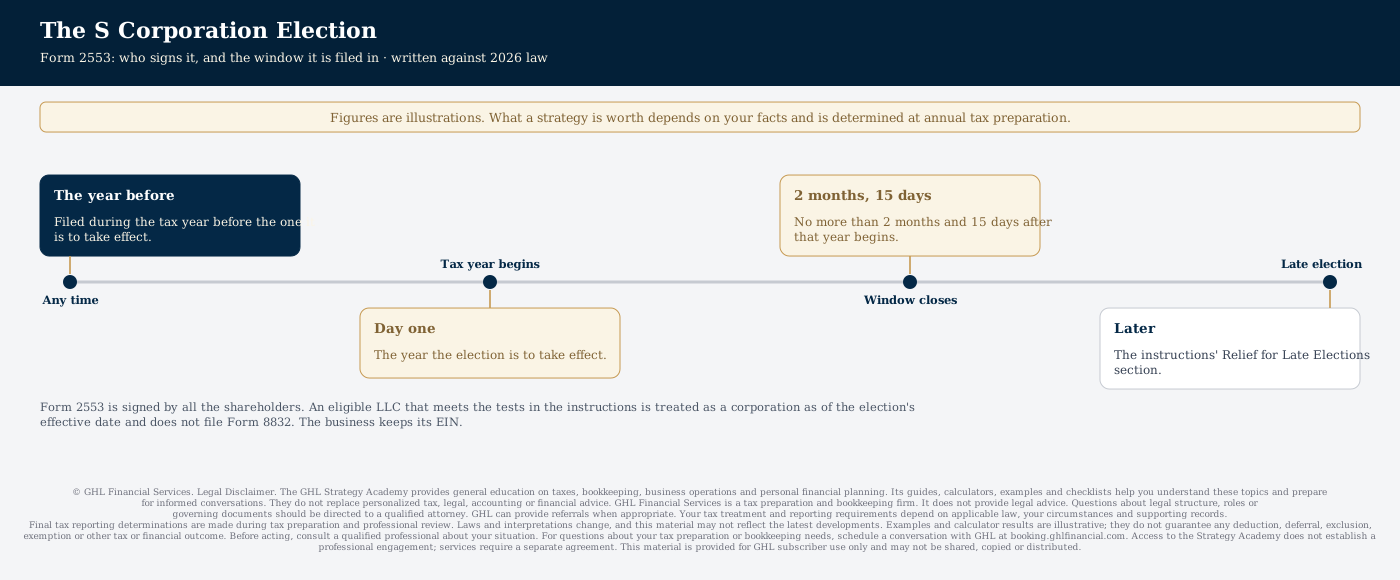
When it matters: No more than 2 months and 15 days after the beginning of the tax year the election is to take effect, or at any time during the tax year before it.
Does this fit you?
- You are weighing S corporation treatment for a corporation or an LLC.
- Your business has more than one owner, each of whom would sign.
- You are not sure your business's Form 2553 was filed.
What it could be worth
The election changes how the business's income is taxed, not what the business is: S corporations pass corporate income, losses, deductions and credits through to their shareholders, and file Form 1120-S. Whether that is worth it is a question about this business's own figures, which the Changing Entity Type and S-Corp Salary guides take up.
This guide is about the form itself: what it does, who signs it, and when it is filed.
How it works
What the form does. IRS.gov: “A corporation or other entity eligible to be treated as a corporation files this form to make an election under section 1362(a) to be an S corporation.”
Who signs. IRS.gov's S corporation page: “In order to become an S corporation, the corporation must submit Form 2553, Election by a Small Business Corporation signed by all the shareholders.” That is every shareholder, not only the ones who run the business.
When. The instructions: “Complete and file Form 2553: No more than 2 months and 15 days after the beginning of the tax year the election is to take effect, or At any time during the tax year preceding the tax year it is to take effect.”
Publication 509 says the same in its calendar: “Form 2553. This form is used to choose S corporation treatment. It is due no more than 2 months and 15 days after the beginning of the tax year the election is to take effect or at any time during the preceding tax year.”
An LLC. By default an LLC is not taxed as a corporation, and it can elect to be. The instructions: “An entity eligible to elect to be treated as a corporation that meets certain tests discussed below will be treated as a corporation as of the effective date of the S corporation election and doesn't need to file Form 8832, Entity Classification Election.” The tests are in the instructions, and whether a particular LLC meets them is a question for a qualified tax professional.
The EIN stays. Among changes that do not need a new EIN, IRS.gov lists, for a corporation: “Choose to be taxed as an S corporation.” And for an LLC: “Change your tax election to a corporation or an S corporation.”
A late election. The instructions have a section headed Relief for Late Elections, linked under Sources. What it asks depends on the business's facts, and this guide does not summarize it.
Not covered here, because the wording has not been checked against IRS.gov: which corporations and shareholders are eligible, where the form is filed, and how the IRS confirms that it accepted the election.
Sources
What you would do
- Write down the tax year the election is meant to take effect, and the window that gives.
- List every shareholder, and collect every signature before filing.
- For an LLC, note the classification question for a qualified tax professional before filing.
- Keep a copy of the filed form, and anything the IRS sends back about it, with the business's permanent records.
- If the window has passed, read the instructions' Relief for Late Elections section and take the question to a qualified tax professional.
Allow one to two months. Some of it depends on other people.
What GHL needs from you
- A copy of the filed Form 2553, with every shareholder's signature.
- Anything the IRS sent back about the election.
- The tax year it was meant to take effect.
- All of it sent through the Secure Client Portal, not by email.
What usually goes wrong
- A shareholder's signature missing. IRS.gov's S corporation page says the form is signed by all the shareholders.
- Counting the window from the wrong date. It runs from the beginning of the tax year the election is to take effect.
- An LLC filing Form 8832 first without reading when the Form 2553 instructions say it is not needed.
- Applying for a new EIN after the election. IRS.gov lists the election among changes that do not need one.
- No copy kept. Years later, the filed form is the record that the election was made.
Common questions
We missed the window. Is that the end of it?
Not necessarily. The Form 2553 instructions have a section headed Relief for Late Elections. What it asks depends on the facts, and this guide does not summarize it.
Do all the owners sign, or only the president?
IRS.gov says the form is signed by all the shareholders.
Our LLC is electing. Does it file Form 8832 first?
The instructions say an eligible entity that meets certain tests discussed there is treated as a corporation as of the election's effective date and doesn't need to file Form 8832. Whether the LLC meets those tests is a question for a qualified tax professional.
Read next
Keeping it alive
A position is not finished when it is set up. This is what it needs each year to still be there when it matters.
- Confirm it still applies — circumstances change more often than the law does.
- Check the documents still say what they said — an agreement that has drifted from practice is the usual failure.
- Ask GHL what changed for 2027. Figures move every year and rules move most years.